The US Securities and Exchange Commission (SEC) has opened a five-year pathway for regulated US stocks to trade on blockchain-native venues.
The Innovation Exemption came two days after the Senate failed to advance the CLARITY Act, a broad crypto market-structure bill that sought to establish statutory rules for digital assets and clarify regulatory responsibilities. The procedural vote failed 49-50, short of the 60 votes needed to move it forward.
That failure left the crypto industry without a comprehensive market-structure framework and put greater weight on what regulators can do under existing law.
SEC Chair Paul Atkins explicitly tied the Sept. 17 action to the stalled legislation, saying the agency was moving “within its statutory authority” to facilitate on-chain trading of certain tokenized stocks.
This move opens the $77 trillion US stock market to crypto-style trading. However, the decision addresses a narrower question of how regulated stocks can trade through blockchain infrastructure. It also pushes US policy closer to a market already developing offshore, where crypto companies are offering tokenized equities that can move beyond conventional exchange hours.
SEC gives on-chain venues a five-year test
The exemption creates a framework for Tokenized Securities Venues (TSVs) that bring buyers and sellers together through permissioned automated market makers and liquidity pools.
Qualifying venues receive temporary relief from being treated as exchanges under the Securities Exchange Act, while certain liquidity providers using their own capital can receive related relief from dealer-registration requirements. The exemptions expire after five years, giving the SEC a window to collect trading data before deciding what a permanent framework should look like.
Commissioner Mark Uyeda described the structure as deliberately constrained. The framework includes symbol and volume caps, along with requirements covering transaction transparency, trading halts, recordkeeping, and technology safeguards. Venues must also publish information including prices, trade sizes, timestamps, pool addresses and daily trading volumes.
The move coincided with an SEC roundtable on preparations for 24-hour US equity trading, reflecting a broader shift toward markets that operate beyond the traditional session.
Atkins said economic and corporate events no longer occur neatly within market hours and investors increasingly want the ability to adjust positions when news breaks. He also pointed to tokenization as a potential tool for real-time inventory management, which could improve efficiency and reduce settlement failures.
Uyeda has similarly argued that tokenization could reduce reliance on intermediaries, streamline transaction lifecycles and lower operational costs, while requiring securities protections to carry over into on-chain markets.
The regulatory opening immediately attracted interest from companies that have spent the past year building tokenized-equity businesses abroad.
Robinhood Crypto General Manager Johann Kerbrat said the exemption signals that tokenization is ready to come to the US.
He said:
“This is a major step by the agency and will allow liquid tokenized securities markets to develop onshore. Smart regulation accelerates innovation.”
Already, several US crypto firms, including Robinhood, Kraken and Coinbase, offer tokenized US equity products to customers in overseas markets.
Tokenized stocks find trading before financial utility
Those offshore markets show that one of tokenization’s most promoted benefits, continuous access to equities, is already attracting meaningful activity.
Token Terminal data show tokenized stocks reached a record $3.2 billion in market capitalization, up 1,219.3% over the past year. The products generated $15.75 billion in decentralized-exchange trading volume over the past 30 days, including $2.95 billion on weekends, when traditional US exchanges are closed.
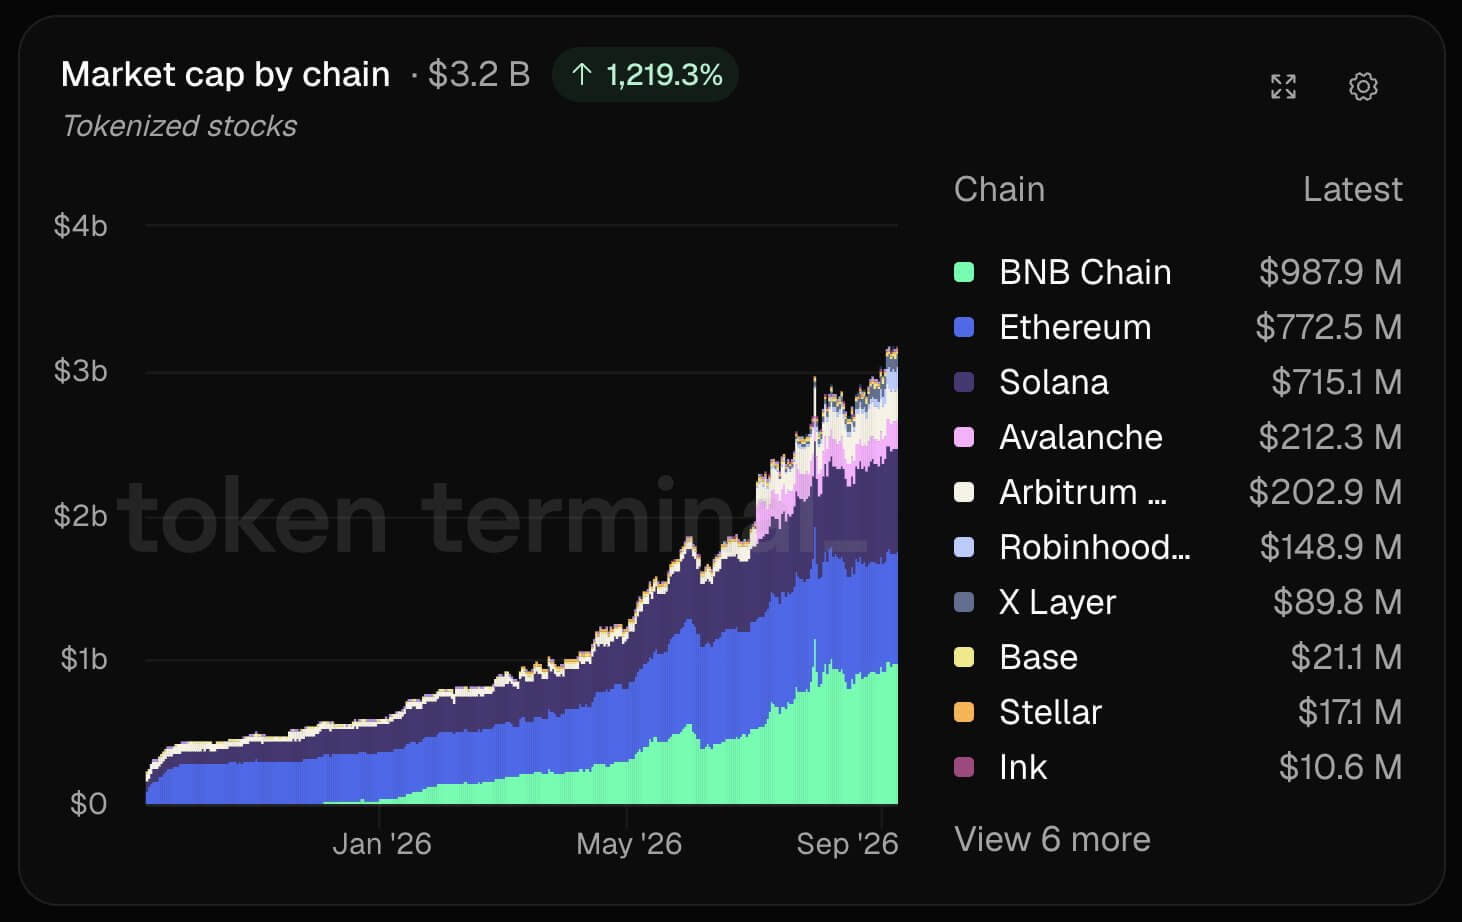
Turnover increased 4.4-fold in three weeks, from $360 million to $1.6 billion per weekend, reinforcing the case that investors are using tokenized equities partly to trade outside conventional market hours.
Token Terminal counted 3.7 million tokenized-stock holders, up 4,247.8% over the past year, though the figure reflects on-chain holders rather than necessarily distinct investors.
Capital is also moving beyond wallets and trading venues into decentralized finance. Tokenized-stock value deployed in DeFi has risen 1,960.8% over the past year to $247.8 million.
Yet trading still represents the market’s dominant use case.
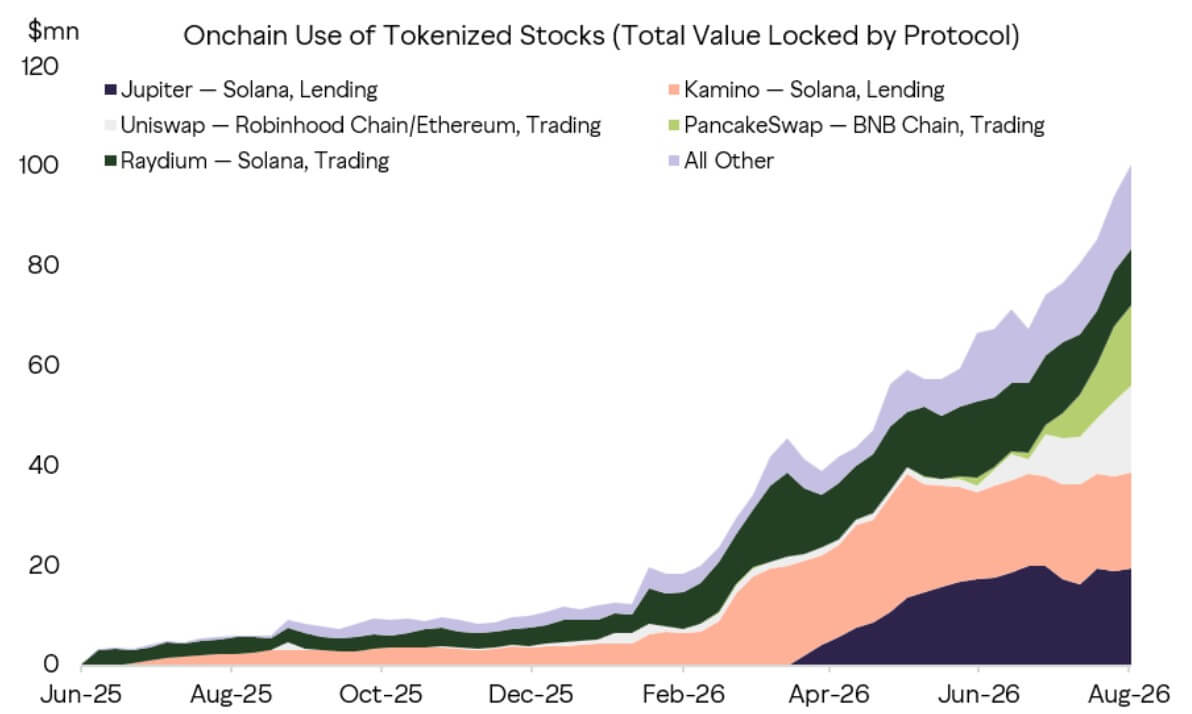
Grayscale estimated in late August that only about 5% of the tokenized-equity market was deployed in on-chain finance, suggesting investors have so far valued continuous trading and global access more than using stocks for lending, collateral, and other financial applications.
The SEC’s new exemption could help broaden that utility.
Grayscale said greater regulatory clarity, including frameworks built around verified participants and compliance-enabled token standards, could make tokenized securities easier to integrate with lending markets and other blockchain-based financial infrastructure.
That would allow tokenized stocks to function as more than assets that can be traded around the clock. They could increasingly serve as programmable collateral or be deployed in lending markets, creating additional financial uses for securities already circulating on-chain.
Early signs of that transition are emerging. Grayscale said tokenized equities deployed in lending protocols such as Solana-based Kamino and Jupiter have increased roughly tenfold over the past year.
The firm said regulatory changes could eventually allow the security and payment legs of a transaction to settle together on-chain, reducing the risk that one party delivers while the other fails to.
The exemption creates a regulated pathway for tokenized securities infrastructure in the US, and it could provide the foundation for platforms to test some of those applications under clearer rules.
Issuer vetoes and trading caps limit the experiment
However, the SEC has placed significant boundaries around that transition.
The exemption applies to tokenized National Market System stocks that represent genuine securities. The tokens must give holders the same rights and privileges as equivalent traditional shares, including dividend and voting rights. Synthetic instruments that merely reproduce a stock's price exposure are outside the framework.
That distinction matters because some tokenized products currently traded overseas are structured differently. Robinhood, for example, describes its Classic Stock Tokens in Europe as blockchain-recorded derivatives rather than ownership of the underlying shares.
Issuers also retain considerable control over what reaches the new venues. Companies must have an opportunity to object when an unaffiliated third party seeks to tokenize their securities, allowing them to prevent their stock from trading through a TSV.
Venues must be US persons, comply with Office of Foreign Assets Control sanctions requirements, and restrict participation through permissioned access. Trading is also subject to limits on the number of stocks and the volumes that can change hands.
Those caps could matter most during overnight and weekend sessions. Extending markets beyond conventional hours can improve access and allow investors to react faster to news, but thin liquidity can also produce wider spreads and sharper price moves.
Atkins acknowledged that tension, saying around-the-clock market infrastructure must preserve functions and protections available during the traditional trading day. He said market activity may also need to deepen before services such as securities lending and prime brokerage can operate effectively overnight.
The five-year exemption now gives regulators and market participants a controlled test of whether they can manage those problems.
For crypto firms building tokenized-equity businesses, it creates a route to move activity that has largely developed offshore into the US regulatory system.
The post After Congress killed its landmark crypto bill, the SEC unlocked the $77 trillion US stock market through tokenization appeared first on CryptoSlate.

Comments (0)
Please sign in to comment.
No comments yet. Be the first to comment.